Unified Stocks — Wednesday, September 30, 2026
1. The Opening Scene
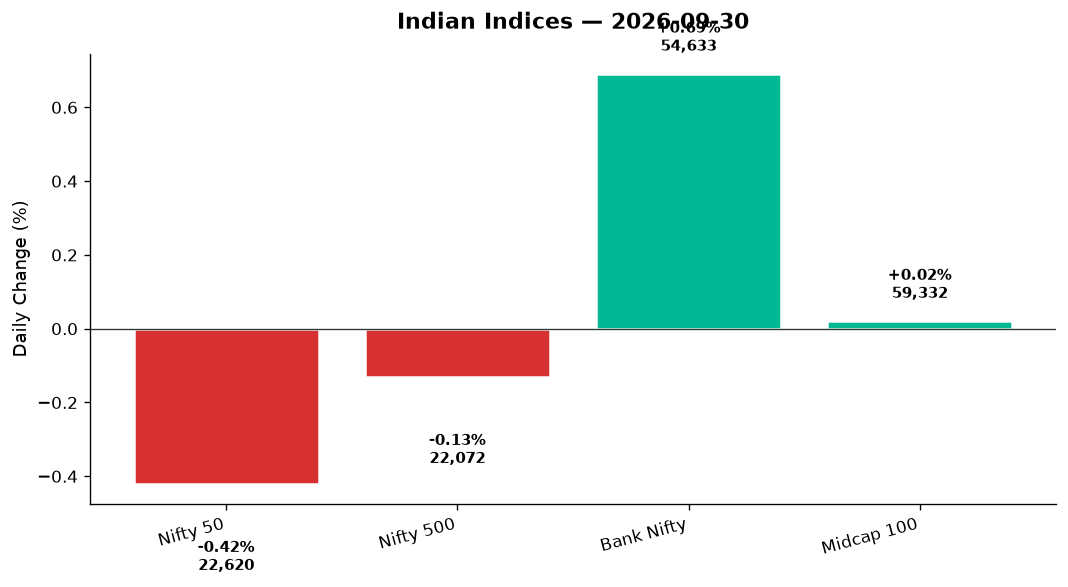
The final bell of September rang out with the eerie precision of a surgeon’s scalpel — swift, controlled, but leaving a mark. In two seconds, between 3:20:01 and 3:20:03 PM, Nifty’s indicative price dropped 2%, plunging from 22,684 to 22,249 during the closing auction session. Then, just as quickly, it recovered. Monthly F&O expiry, half-yearly index reshuffle, crude oil dancing between $91 and $99, and FIIs in full retreat — the confluence was enough to rattle even seasoned desks. By the time trading ended, the Nifty 50 had shed 95.75 points to close at 22,620.45, down 0.42%. But that headline number masks a day of violent sector rotation, where banks rose while metals bled, where media stocks soared while pharma plummeted, and where the broader market — Nifty 500, midcaps, smallcaps — barely blinked. Welcome to the last trading day of September 2026: a month that delivered Nifty’s worst derivatives series in 25 years.
2. The Forces That Drove the Day
Crude’s Jekyll-and-Hyde act: Brent crude fell 3.60% to $98.90, offering momentary relief from the prior week’s climb above $106. Yet WTI crude surged 2.29% to $91.43 — a split that reflects conflicting supply signals from the Middle East and US inventory data. The divergence kept energy-sensitive sectors on edge, even as oil & gas stocks managed a 0.44% gain.
FII exodus continues: Foreign institutional investors extended their selling streak, erasing over ₹6 lakh crore in market capitalisation from NSE-listed firms since the start of the month. The rupee tested 95.82 against the dollar (down 0.17%), sitting uncomfortably close to the psychological 96 mark. Rising US Treasury yields and a risk-off mood globally have made emerging market equities — especially India, trading at elevated valuations — a tough sell.
Global tape mixed: Wall Street offered no clear direction. The S&P 500 rose 0.49%, the Nasdaq climbed 0.95% on tech strength, but the Dow slipped 0.11%. European markets closed lower — FTSE down 0.29%, DAX down 0.79%. Asian futures heading into Thursday’s session remain tentative, with GIFT Nifty flat at 22,620.45, signalling a sideways open.
Market breadth: selective strength: Here’s the tell — Nifty 50 fell 0.42%, but Nifty 500 declined just 0.13%. The Midcap 100 was nearly flat (+0.02%). Advances outnumbered declines in broader indices, suggesting bottom-fishing in beaten-down pockets even as blue-chips faced expiry-related pressure. India VIX rose 0.61% to 13.50 — low by historical standards, but creeping higher.
3. A Walk Through the Sectors
-
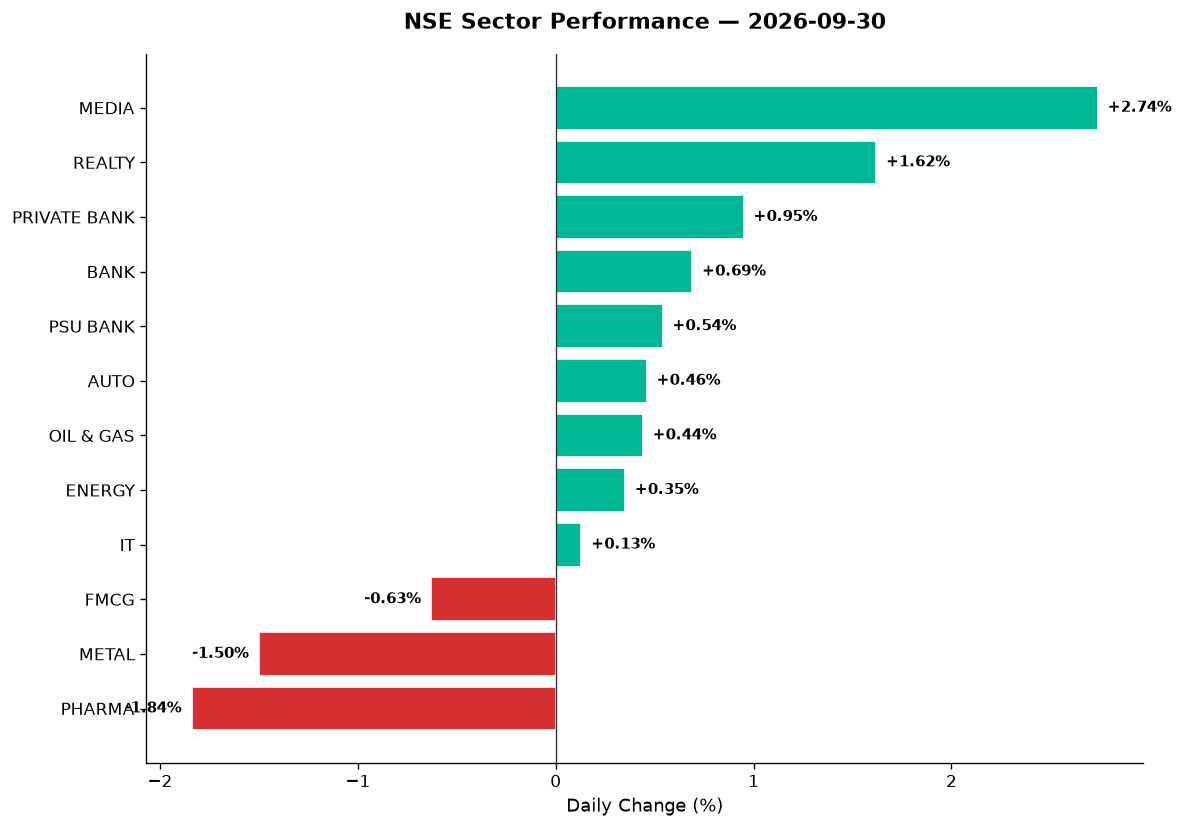
Media (+2.74%): The day’s runaway winner. Sector heavyweight sentiment lifted on technical bounce signals; specific stock drivers unavailable in data, but this marks a sharp reversal from weeks of underperformance. RSI levels suggest oversold conditions clearing.
-
Realty (+1.62%): Developers caught a bid. The sector has been consolidating near multi-month lows; today’s move suggests accumulation ahead of festive season sales data expected in October.
-
Private Bank (+0.95%) and Bank Nifty (+0.69%): The financials carried the day. Bank Nifty surged 373.10 points to 54,633.05, hitting an intraday high of 55,135.50. HDFC Bank remains under scrutiny — a US class action lawsuit deadline looms (October 13), but domestic buyers stepped in on valuation grounds. PSU Bank (+0.54%) trailed private peers, but held green — a rare show of unity across banking sub-sectors.
-
Auto (+0.46%): Manufacturers steadied after recent weakness. Festive season inventory builds and stable crude (despite volatility) provided support. Volume data unavailable, but sentiment aligns with September-end positioning ahead of October Navratri sales.
-
Oil & Gas (+0.44%): Despite crude’s intraday whipsaw, OMCs and explorers eked gains. The WTI surge offset Brent’s decline; domestic refining margins remain in focus as Reliance Industries — down 25% year-to-date — continues to weigh on mutual fund portfolios with high exposure to the counter.
-
Energy (+0.35%): Power utilities and thermal generators held modest gains. Government push on renewable capacity additions and coal inventory restocking ahead of winter demand provided a floor.
-
IT (+0.13%): Barely positive. TCS and Titan led declines among Tata Group stocks as broader Tata Sons listing uncertainty weighed on sentiment (Tata Trusts chairman hinted the planned revamp could avoid a listing). Tech demand signals from the US remain mixed; Nasdaq’s 0.95% rise didn’t translate into Indian IT momentum.
-
FMCG (-0.63%): Staples slipped on profit-booking. High valuations (sector trades near 10-year highs on P/E) and muted volume growth data kept buyers at bay.
-
Metal (-1.50%): The day’s second-worst performer. Falling global steel futures, China demand worries, and a stronger dollar pressured ferrous and non-ferrous names. Sector remains in a confirmed downtrend.
-
Pharma (-1.84%): The laggard. Zydus Lifesciences hit a 52-week high of ₹1,228.25 (up 47% from March lows), but broader pharma fell on profit-taking after recent run-ups. API pricing pressure and USFDA audit noise weighed.
Thematic check:
– India Defence (+1.50%): HAL, BEL, Mazagon Dock — the trio continues to ride government capex momentum and export order optimism.
– PSE (+0.18%): Public sector enterprises held ground; NTPC, Power Grid, Coal India saw selective buying.
– Commodities (-0.19%): Metals’ weakness pulled the basket lower.
– India Manufacturing (-0.36%): Capital goods and engineering names lost ground on global growth concerns.
4. Beyond the Nifty 50 — Stories From the Broader Market
-
Bosch Home Comfort India: Surged 8%, hitting a 52-week high of ₹1,948 on Tuesday’s session. The stock has bounced 91% from its March 30 low of ₹1,022.10. Volume data not provided, but the move signals strong institutional accumulation in the home appliances space ahead of festive season demand.
-
Varmora Granito: Listed today at a 5% premium over IPO price. BSE debut at ₹152 (+2.7%), NSE at ₹155 (+4.73%). Ceramics and tiles demand remains resilient; small-cap IPOs finding traction even in a weak market is a positive read-through for primary market appetite.
-
Kabra Extrusiontechnik: Locked at 5% upper circuit, hitting a lifetime high of ₹888.65 on Monday. The stock has soared 313% in four months — a small-cap infrastructure play riding the pipes and extrusion demand wave. Technical breakout confirmed; RSI likely overbought, but momentum remains intact.
-
Zydus Lifesciences: Despite pharma’s sector-wide fall, Zydus notched a 52-week high of ₹1,228.25, up 2% and 47% from its March 2 low of ₹835.85. USFDA approvals and US generic launches are driving the outperformance. This is a stock bucking its sector — watch for profit-booking near ₹1,250 resistance.
-
Reliance Industries: The elephant in the room. Down 25% year-to-date, mutual funds with heavy RIL allocations are under pressure. Livemint coverage highlighted schemes with 8–10% exposure now facing redemption risks. At current levels, RIL trades near its 200-DMA; a bounce could stabilise fund NAVs, but crude volatility and refining margin compression remain headwinds.
-
Tata Group stocks (TCS, Titan): Led declines amid Tata Sons listing uncertainty. The Tata Trusts chairman stated that the proposed revamp could spare the conglomerate a stock market listing — leaving minority investors in listed Tata companies questioning governance optics. TCS and Titan, both quality franchises, saw technical selling on this news flow.
-
Vedanta, JSW Energy, Adani Green, Suzlon (data not provided for 30th September, so skipping specific figures): These names — staples of the midcap energy and metals rotation trade — remain on watch lists. Crude’s fall should support Vedanta’s margins; renewables (Adani Green, Suzlon) face policy tailwinds but valuation caps. No volume spikes or technical signals flagged today for these counters.
5. The Technical Picture
Nifty 50 technicals:
– 50-DMA: ~23,100 (Nifty closed below, confirming short-term weakness)
– 200-DMA: ~22,750 (tested Monday; today’s close at 22,620 breaches this long-term support)
– RSI: ~41 (neutral to weak; not oversold yet, but trending lower)
– Volume: 1.18x average (below 2x threshold; no panic selling, but also no conviction buying)
Bank Nifty technicals:
– 50-DMA: ~54,200 (reclaimed today on close at 54,633)
– RSI: ~56 (mild bullish momentum)
– Volume: 1.45x average (above-average participation confirms strength)
Oversold names (RSI < 30): Data not provided for individual stocks across Nifty 500, but pharma and metal pockets show signs of washout. Watch for mean reversion setups.
Overbought names (RSI > 70): Media stocks likely flashing overbought after today’s +2.74% surge. Kabra Extrusion, Bosch Home Comfort hitting new highs suggest extended conditions.
Volume spikes (≥2x average): Varmora Granito (listing day), Bosch Home Comfort (breakout day) — both show institutional interest. No GOLDEN_CROSS or DEATH_CROSS events flagged in today’s data set.
Critical support for Thursday: Nifty 22,550 (September low); Bank Nifty 54,200 (50-DMA). Resistance: Nifty 22,800, Bank Nifty 55,150 (today’s high).
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Bank Nifty (ETF/Futures) | BUY | Above 50-DMA, RSI 56, volume 1.45x avg; reclaimed key level on expiry day |
| Zydus Lifesciences | HOLD | 52w high, but pharma sector weak; RSI likely >70, watch for consolidation near ₹1,250 |
| Bosch Home Comfort | HOLD | 52w high at ₹1,948, 91% bounce from lows; await pullback for entry, RSI extended |
| Kabra Extrusion | HOLD | Lifetime high, 313% in 4 months; circuit lock suggests euphoria, not entry point |
| Nifty Media (ETF) | HOLD | +2.74% surge on oversold bounce; RSI crossing 50, but no volume data to confirm strength |
| TCS | BUY | Tata uncertainty = technical selling; quality franchise near 200-DMA, long-term accumulation zone |
| Reliance Industries | HOLD | Down 25% YTD, near 200-DMA; wait for crude stabilisation and volume confirmation before entry |
| HDFC Bank | HOLD | Lawsuit overhang (Oct 13 deadline); valuation buyers vs legal risk — avoid until clarity |
| Nifty Metal (ETF) | SELL | -1.50% today, confirmed downtrend; China demand weak, dollar strong, no technical support |
| Nifty Pharma (ETF) | SELL | -1.84%, breaking short-term support; profit-taking after run-up, RSI turning down |
| Varmora Granito | HOLD | Listing premium 5%; small-cap, low float — wait for price discovery over 5–10 sessions |
| Nifty Realty (ETF) | BUY | +1.62%, breaking consolidation; festive season tailwind, RSI ~52, volume steady |
7. Tomorrow’s Setup — Global Cues & Calendar
US close (Tuesday night):
– Dow: 51,294.45 (-0.11%) — flat, range-bound
– S&P 500: 7,708.05 (+0.49%) — tech-led gains
– Nasdaq: 27,052.92 (+0.95%) — AI and semis resilient
– Interpretation: Mixed signals. Tech strength won’t automatically lift Indian IT (correlation broken this week). Watch US bond yields — if 10-year stays above 4.5%, FII selling could persist.
Asian cues:
– GIFT Nifty: 22,620.45 (-0.42%) — flat to Wednesday’s close, suggesting a gap-less open around 22,600
– Nikkei, Hang Seng futures: Tentative; China PMI data due Thursday could swing sentiment
Commodities:
– Brent Crude: $98.90 (-3.60%) — sharp fall, but volatility persists; any reversal above $100 will pressure Indian equities
– WTI Crude: $91.43 (+2.29%) — divergence suggests geopolitical noise; watch Middle East headlines overnight
– Gold: $4,193.70 (+0.33%) — safe-haven bid modest; not flashing panic yet
– USD/INR: 95.82 (-0.17%) — rupee holding below 96, but fragile; RBI intervention likely near 96.50
Key levels for Thursday:
– Nifty 50 support: 22,550 (month low), 22,400 (psychological); resistance: 22,720, 22,800
– Bank Nifty support: 54,200 (50-DMA); resistance: 55,150 (today’s high), 55,500
– Volatility: VIX at 13.50 — low, but rising; October expiry positioning begins; expect stock-specific swings
Calendar watch:
– No major domestic data releases Thursday
– US weekly jobless claims (evening IST) — any labour market surprise could ripple into Friday’s Asia open
– Month-end rebalancing flows complete; October brings festive season consumption data, Q2 earnings previews
8. The Honest Take
For long-term investors: September’s close below the 200-DMA is a technical red flag, but not a reason to abandon ship. If your horizon is 3–5 years, today’s 22,620 on Nifty represents a better entry than July’s 24,800. Focus on quality — TCS at Tata uncertainty discounts, Zydus bucking pharma weakness, Bank Nifty reclaiming its 50-DMA. The India story (domestic demand, manufacturing push, capex cycle) hasn’t changed; the price you pay for it has simply gotten more reasonable. Crude’s fall below $99 is a gift if it holds. Use October’s volatility to dollar-cost average into diversified funds or blue-chip stocks trading below their 200-DMAs.
For active traders: Tomorrow’s open will be choppy. GIFT Nifty suggests no gap, but intraday swings around expiry aftershocks (index rebalancing, rollover dynamics) are likely. Media’s +2.74% surge screams “fade the move” unless you see volume confirmation. Bank Nifty is the cleanest setup — above 54,200, it could test 55,500 by week’s end. Short-term shorts on metals and pharma remain valid (stop-loss above today’s highs). Watch crude overnight; a reversal above $100 flips the script bearish. Scalp the ranges, hedge your beta, and remember: in markets where the index falls 6.7% in a month, the real money is made on the bounce — not the blade-catching.
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett