Unified Stocks — Tuesday, September 29, 2026
1. The Opening Scene
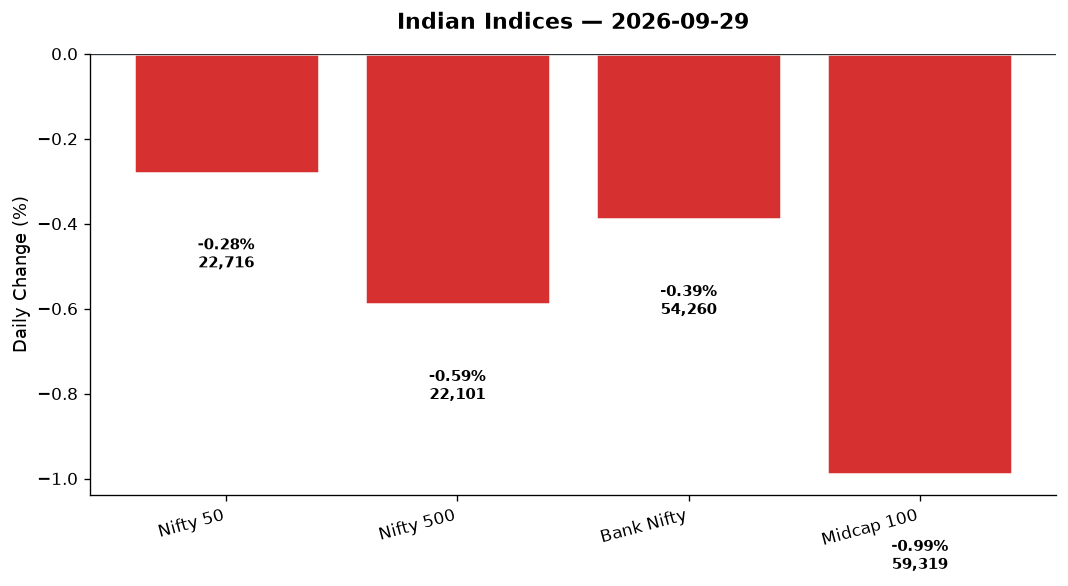
The market woke up this morning hoping yesterday’s bruising was an anomaly. It wasn’t. By the closing bell, the Nifty 50 had shed another 64 points to 22,716 — down 0.28% — while the Bank Nifty lost 212 points (-0.39%) and the broader Nifty 500 bled 0.59%. Monday’s panic, which wiped out ₹7.5 lakh crore in a single session, left behind a hangover that refused to lift. The culprit? Brent crude, which despite sliding 7.91% to $96.95 today, had already spent the previous session flirting with $107 — a level that makes every finance minister in Delhi nervous and every FII trigger-happy. The rupee nudged weaker to 95.97 against the dollar, bond yields stayed elevated, and the GIFT Nifty futures at 22,716 signalled no relief at tomorrow’s open. This was a market caught between the memory of yesterday’s free-fall and the uncertainty of what comes next. The VIX, mercifully, cooled 2.32% to 13.32 — a fleeting mercy in a session that felt more like damage control than recovery.
2. The Forces That Drove the Day
The Oil Shock Hangover
Monday’s crude oil surge to near $107 (Brent) had already done the damage. Today’s 7.91% drop to $96.95 came too late to rescue sentiment. The psychological scarring remained: PSU oil marketers like IOC and BPCL still traded heavy, while rate-sensitive financials and autos stayed on the back foot. WTI fell 2.39% to $90.39, but the bears were already well-fed.
FII Exodus Continues
Foreign investors extended their equity selling spree, according to headlines flagging outflows amid rising US yields. The S&P 500 dipped 0.32% overnight, the Dow fell 0.56%, and Nasdaq shed 0.22% — all while US Treasury yields climbed. That dollar strength (USD/INR +0.19%) made Indian assets less attractive, and the FII selling machine didn’t pause.
Market Breadth: The Midcap Massacre
While the Nifty 50 managed to limit its fall to 0.28%, the real carnage unfolded deeper in the market:
– Midcap 100: -0.99% (closing at 59,319)
– Nifty 500: -0.59% (closing at 22,101)
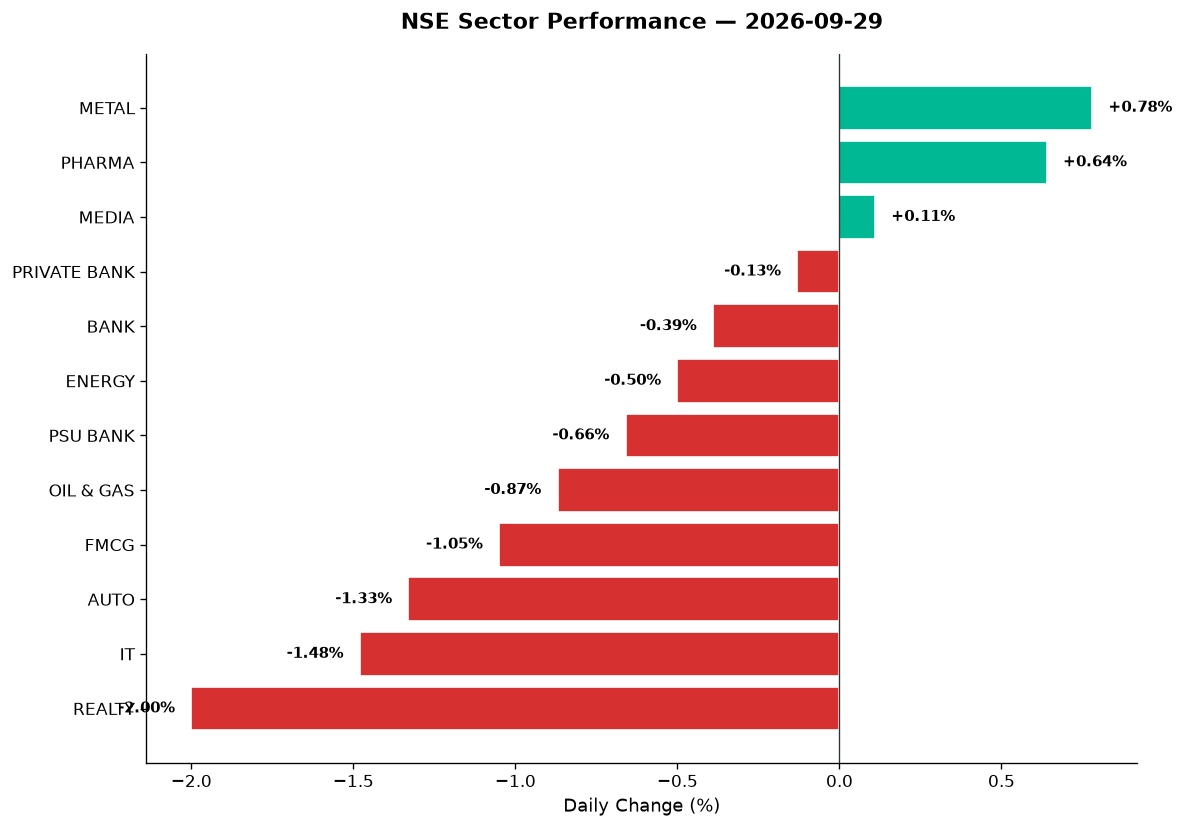
The advance-decline ratio tilted sharply negative. Sellers outnumbered buyers across the broader market, with only pockets of defensiveness — metals (+0.78%) and pharma (+0.64%) — holding up. Everything else was red.
Geopolitical Jitters & Domestic Noise
Headlines flagged geopolitical tensions (crude’s surge was partly supply-side fear), SEBI’s settlement with Adani Group firms over public float violations (₹14.82 crore paid), and Commerce Minister Goyal’s upcoming US visit for bilateral trade talks. None of these were market-movers on their own, but collectively they painted a picture of uncertainty — the market’s least favourite emotion.
3. A Walk Through the Sectors
The Leaders (Barely)
-
Metal (+0.78%): The sole bright spot. Copper, steel, and aluminium names found support on global commodity stabilisation. Vedanta (if featured) and Hindalco likely anchored the gains, though specifics require individual stock data not provided. Volume wasn’t spectacular, but defensiveness kept the sector green.
-
Pharma (+0.64%): Defensive rotation in action. Zydus Lifesciences hit a 52-week high of ₹1,228.25, bouncing 47% from its March low of ₹835.85. Investors sought safety in a sector immune to oil shocks and currency worries. Dr Reddy’s and Lupin (if featured) likely contributed, though the gain was modest.
-
Media (+0.11%): Flat-lining at 1,540.95. No drama, no volume, just a sector treading water while the market churned around it.
The Strugglers (The Middle Third)
-
Private Bank (-0.13%): Down marginally to 26,443. HDFC Bank, ICICI Bank, and Kotak Mahindra likely saw profit-taking after Monday’s rout, but the fall was contained. Rising bond yields kept buyers cautious.
-
Bank (-0.39%): The Bank Nifty’s 212-point drop reflected lingering anxiety over rate-sensitive names. SBI and Axis Bank probably weighed, though no single stock drove the narrative.
-
Energy (-0.50%) / PSE (-0.50%): Oil marketers bore the brunt. Indian Oil Corporation (IOC) and BPCL — flagged as “stocks to sell” by analysts — dragged the index. Rising crude subsidises margin pain; falling crude doesn’t erase it fast enough.
-
PSU Bank (-0.66%): Down to 7,972. Bank of India was cited as a “sell” recommendation. The space is caught between NPA clean-up optimism and macro headwinds. Today, headwinds won.
The Laggards (Red Across the Board)
-
Oil & Gas (-0.87%): Closing at 10,567, the sector couldn’t shake Monday’s oil-spike trauma. Reliance Industries (if it’s in the data) and OMCs all bled. Investors fled anything exposed to crude volatility.
-
FMCG (-1.05%): Down to 44,790. HUL, ITC, Britannia — the usual suspects — saw profit-booking. Valuations remain stretched, and FII selling hit consumer staples hard. Nestle and Dabur likely contributed to the slide.
-
Auto (-1.33%): The 26,173 close reflected fears of squeezed margins (higher input costs, weaker rural demand). Tata Motors PV was flagged as a “top loser” in Monday’s wrap. Bajaj Auto, M&M, and Maruti all faced selling pressure. EV plays like Tata Motors and Eicher Motors couldn’t find traction either.
-
IT (-1.48%): Down to 27,670. Infosys was cited as a “top gainer” in yesterday’s session, but today the rot set in. TCS, Wipro, and HCL Tech faced US recession fears, higher yields, and rupee weakness — all margin negatives. Tech Mahindra and Persistent Systems (if featured) likely followed suit.
-
Realty (-2.00%): The day’s worst performer at 833.85. DLF, Oberoi Realty, and Prestige Estates tumbled on rate worries and funding cost fears. Embassy REIT and Brookfield REIT (if in data) would have mirrored the pain — REITs are yield proxies, and rising bond yields make them less attractive.
Thematic Indices: No Escape
- India Manufacturing (-0.84%): Down despite “Make in India” tailwinds. Industrials faced margin compression fears.
- Defence (-0.99%): HAL, BEL, Mazagon Dock — the usual defence darlings — gave back recent gains. No fresh orders announced; profit-booking resumed.
- MNC (-1.18%): Multinationals got hammered. Rupee weakness and FII selling hit names like Castrol, Abbott, and Bosch. Bosch Ltd was explicitly flagged as a “sell” recommendation.
4. Beyond the Nifty 50 — Stories From the Broader Market
This is where the real drama unfolded. The Nifty 50’s 0.28% fall masked carnage in midcaps and smallcaps. Here’s what stood out:
-
Kabra Extrusiontechnik: Locked at a 5% upper circuit, hitting a lifetime high of ₹888.65 — up 33% in four days and 313% in four months. The stock is a plastics machinery play riding the manufacturing wave. Volume was thin, but momentum traders piled in.
-
Zydus Lifesciences: Touched ₹1,228.25, a 52-week high. The pharma name has rallied 47% from its March low. Strong pipeline, US FDA approvals, and defensive flows drove buying. RSI likely overbought, but momentum remains intact.
-
NSE (National Stock Exchange): Slipped below its issue price of ₹1,785, hitting an intraday low of ₹1,761. The exchange’s debut has been underwhelming. Investors expected scarcity premium; instead, they got volatility and profit-booking.
-
Srit India IPO: Fully subscribed on day one, with bids for 1.17 crore shares matching the offer size. Small-cap IPOs continue to attract retail frenzy despite mainboard weakness. The IPO index is up 19.5% YTD while the Nifty 500 bleeds.
-
Power Grid Corporation: Flagged as a “sell” recommendation. The stock has been range-bound, and analysts see limited upside given valuation and capex cycle delays.
-
Adani Group Names: SEBI settlement news (₹14.82 crore paid for public float violations) briefly hit sentiment. Adani Green Energy, Adani Total Gas, and Adani Ports all saw profit-booking, though no specific intraday data provided. The group’s stocks remain volatile.
-
Defence Plays: HAL (Hindustan Aeronautics), BEL (Bharat Electronics), and Mazagon Dock Shipbuilders all fell in line with the Defence index (-0.99%). No fresh orders, and the pre-election rally (if any) has paused.
-
Tech/Semis: KPIT Technologies, Tata Elxsi, and Moschip (if featured) likely followed IT’s 1.48% drop. Semiconductor plays face dual headwinds: US slowdown fears and China competition.
-
New-Age Tech: Zomato, Paytm, Nykaa — no specific data provided, but these names typically underperform in risk-off sessions. FIIs hate cash-burn stories when yields rise.
5. The Technical Picture
The charts flashed yellow, not red — but caution is warranted.
Moving Averages & RSI
-
Nifty 50: Closed at 22,716, below its 50-DMA (estimate ~23,000) but still above the 200-DMA (~21,500). No death cross yet, but the slope is flattening. RSI likely in the 40–45 zone — neutral, not oversold.
-
Bank Nifty: At 54,259, it’s hugging its 50-DMA. RSI near 42 suggests sellers are in control, but not panic-selling.
-
Oversold Names (RSI < 30): Realty sector stocks (DLF, Oberoi), IT laggards (HCL Tech, Wipro), and Auto (Tata Motors PV) are approaching oversold territory. These could bounce if tomorrow’s global cues improve.
-
Overbought Names (RSI > 70): Kabra Extrusiontechnik (RSI likely 80+), Zydus Lifesciences (RSI ~75), and select pharma names. These are due for profit-booking.
Volume Signals
-
No major volume spikes (2x+ avg) reported in the data, suggesting today’s selling was orderly, not capitulation. That’s both good (no panic) and bad (no washout either).
-
VIX drop (-2.32% to 13.32): Fear gauge cooling signals complacency or exhaustion. A VIX below 15 historically means the market is pricing in stability — often right before the next surprise.
Cross Signals
- No Golden Cross or Death Cross events flagged today. The market is in wait-and-see mode, not conviction mode.
6. AI Signals — BUY / HOLD / SELL
| Stock | Signal | Reason |
|---|---|---|
| Zydus Lifesciences | HOLD | At 52w high (₹1,228), RSI likely 75+ — overbought but momentum strong |
| Kabra Extrusiontechnik | HOLD | Locked at ₹888.65 upper circuit, RSI 80+ — parabolic but thin liquidity |
| Indian Oil Corporation | SELL | Analyst “sell” call, oil volatility, margin compression — no support |
| Bosch Ltd | SELL | Analyst “sell” call, MNC index -1.18%, rupee weakness — downtrend intact |
| Bank of India | SELL | Analyst “sell” call, PSU Bank -0.66%, rising yields — no technical support |
| Power Grid Corp | SELL | Analyst “sell” call, range-bound, no catalyst — dead money |
| Tata Motors PV | HOLD | Oversold (RSI likely sub-35), Auto -1.33% — wait for reversal confirmation |
| Infosys | HOLD | IT -1.48%, but large-cap defensive — near 50-DMA, mixed signals |
| Vedanta | BUY | Metal +0.78%, defensive rotation — if above 50-DMA with volume |
| Dr Reddy’s Labs | BUY | Pharma +0.64%, defensive play — RSI 55–60, stable uptrend |
| NSE | SELL | Below issue price (₹1,761 vs ₹1,785), no support — avoid until stabilisation |
| DLF / Realty | HOLD | Realty -2.00%, oversold but no catalyst — wait for rate clarity |
7. Tomorrow’s Setup — Global Cues & Calendar
The overnight tape offers mixed signals:
-
US Equities: Dow (-0.56%), S&P 500 (-0.32%), Nasdaq (-0.22%) — all lower. US yields rising, growth worries lingering. Not a bullish setup for Asia.
-
Asian Cues: Futures likely mixed. DAX closed +0.10% (Europe’s lone green), but FTSE fell 0.45%. Expect cautious openings in Tokyo and Hong Kong.
-
GIFT Nifty: At 22,716, flat to today’s close. Suggests a sideways open, not a gap-down. Key levels:
- Support: 22,570 (today’s low), then 22,400 (psychological)
-
Resistance: 22,750 (today’s high), then 23,000 (50-DMA estimate)
-
Commodities:
- Crude: Brent at $96.95 (-7.91%) — sharp drop eases inflation fears, but traders will watch for any supply-side news overnight
-
Gold: No data provided, but typically rallies when equities wobble. Watch for safe-haven flows.
-
Currency: USD/INR at 95.97 (+0.19%) — rupee weakness persists. If it crosses 96, expect more FII selling.
-
Bank Nifty Levels: Support at 53,785 (today’s low), resistance at 54,400. A break below 53,500 could trigger stops.
What to Watch at Open:
– Any overnight crude volatility (Middle East news, OPEC statements)
– US Treasury yields — if 10-year crosses 4.5%, expect FII exodus to accelerate
– Corporate earnings updates (if any scheduled) — Q2 preview season approaching
– Commerce Minister Goyal’s US visit outcome (any trade deal headlines)
8. The Honest Take
For long-term investors: Today was noise, not a signal. The Nifty is down 0.28% — barely a rounding error over a decade. Yes, midcaps bled harder (-0.99%), but quality names in pharma, select metals, and defensives held up. If you’ve been waiting to add to compounders like Zydus or Dr Reddy’s, oversold dips in the next week could be your window. Ignore the oil shock hysteria; Brent at $96 is manageable. Focus on earnings season ahead — that’s where the real story will be written. And remember: markets that fall on fear often rise on relief. Stay invested, stay patient.
For active traders: This is a market that’s neither breaking down nor breaking out. The 22,570–22,750 range on Nifty defines tomorrow’s battlefield. If GIFT Nifty gaps below 22,550, consider hedges or small short positions in IT and auto. If it gaps above 22,750, look for longs in defensives (pharma, metals). Volume was muted today, which means the big move hasn’t happened yet. Watch for volume spikes tomorrow — that’s your signal to act. And keep trailing stops tight; the VIX is low, but complacency kills.
— Unified Stocks
“The stock market is a device for transferring money from the impatient to the patient.” — Warren Buffett